
Zero trust security
The global zero-trust security market is expanding rapidly as a result of increased demand from industries such as BFSI, IT, and telecommunications. To strengthen their market positions and meet the demands of enterprises across verticals, major players have chosen alliances and new product development as their primary organic growth strategies.
Dominant Key Players on Zero Trust Security Market Covered Are:
- Akamai Technologies (US)
- Cisco Systems Inc (US)
- IBM Corporation (US)
- Google (US)
- Check Point Software Technologies (Israel)
- Palo Alto Networks Inc. (US)
- Symantec Corporation (US)
- Pulse Secure (US)
- OKTa (US)
- Cloudflare (US)
- Forcepoint (US)
- Centrify (US)
- Illumio (US)
- Cyxtera Technologies (US)
- Sophos Group PLC (UK)
The zero trust is a security model is focused on the concept of enforcing strict access controls and not trusting others by default, even those that are already within the network's perimeter. The model is designed in such a way that strict identity verification is required for any individual or device attempting to access resources on a private network, regardless of whether they are within or outside the network perimeter. It is a comprehensive approach to network security that combines different technologies.
The high incidence of target-based cyber-attacks is the primary reason for the widespread implementation of zero-trust security solutions. Other factors driving the market include the rising number of cyber vulnerabilities as a result of the adoption of cloud-based services and increased digitalisation. Regulations such as the European Union's General Data Protection Regulation (GDPR) and California's Consumer Privacy Act (CCPA) in the United States are also expected to push the zero-trust security market. The budgetary limitations of SMEs are expected to be a barrier to market development.
The global zero-trust security industry has been segmented based on authentication type, solution type, deployment, organization size, and vertical.
- By authentication type, the global zero-trust security industry has been segmented into single-factor authentication and multi-factor authentication.
- By solution type, the global zero-trust security industry has been divided into data security, network security, API security, security analytics, endpoint security, security policy management, security orchestration automation and response (SOAR), and others.
- By organization size, the global zero-trust security industry has been divided into small- and medium-sized enterprises (SME) and large enterprises.
- Based on deployment, the global zero-trust security industry has been divided into on-premise and cloud.
- Based on vertical, the global zero-trust security industry has been divided into banking, financial services and insurance, energy & power, IT & telecom, government & defense, healthcare, retail & e-commerce, and others.
The geographic analysis of the zero-trust security industry has been conducted for North America, Asia Pacific, Europe, the Middle East & Africa, and South America.
North America has the highest market share because it is the most technologically advanced nation with a high rate of digitalisation. Along with this, government regulations like the CCPA regulations (implemented on January 1, 2020), which are strictly for data protection and information security, are expected to drive the market. The United States leads the market in North America due to its strong adoption of digital transformation, large volumes of critical data generated, and the country's highest-need for zero-trust security solutions.
Due to the large number of cyber threats associated with the adoption of cloud-based services, Asia Pacific is set to be the fastest-growing region in the global zero-trust security market during the forecast period.
[edit] Related articles on Designing Buildings
Featured articles
Check out some of the best features and news from Designing Buildings as well as key stories from around the web.
Rethinking passive fire protection in design
PFP demands the same level of design rigour as structure or services.
38% of Gen Zs feel safe when a fire door is wedged open.
Stunning images from around the world
Shortlist for CIOB’s Art of Building photography competition.
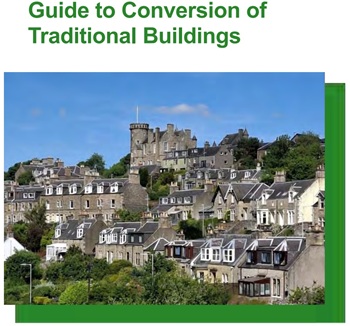
Guidance for conversion of traditional pre-1919 stone buildings.
Industrial heritage in the Ruhr
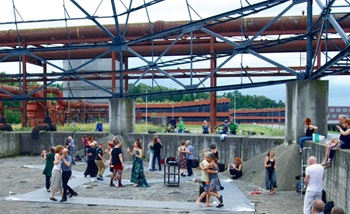
A marked difference to the fate of industrial landscapes in the UK.
Communities will be able to build their own clean energy.
Why diversity and inclusion matters for SMEs
CIOB’s D&I Charter shows how practical changes can support long-term growth.
Cut electricity bills to power growth
Coalition sends joint letter to the Chancellor.

Gasholders: a history in pictures. Book review.
Recognition, influence and growth
SocEnv identifies three strategic pillars in new strategy to 2045.
Discover the future of roofing, cladding and insulation.
New guidance for professional practice, cultural change and regulation in social housing.